Exit Strategy Options – Initial Public Offering (IPO)
Exit strategies are pivotal elements in the lifecycle of any business. Explore exit strategy options with an Initial Public Offering (IPO). Understand the IPO process, which involves offering equity to the public for the first time.
Introduction
An Initial Public Offering (IPO) is the process by which a privately held company becomes public by offering its shares to the general public for the first time. This transformation is often a pivotal exit strategy for early investors and founders, providing a method to realise the value of their private investment while also raising significant capital for the company.
A business owner can choose from several exit pathways, such as a direct listing or a traditional IPO, each with unique impacts on the business. This article explores the IPO as an exit strategy, detailing the intricate process involved when a privately held company decides to go public.
To understand the modern IPO, it helps to look at its origins. The first IPO can be traced back to the Dutch East India Company’s initial public offering in 1602. By offering shares to the public on the Amsterdam Stock Exchange, the company raised significant equity capital to fund its trading operations. This example set the precedent for using public markets to fund large-scale ventures and established the IPO as a viable strategy.
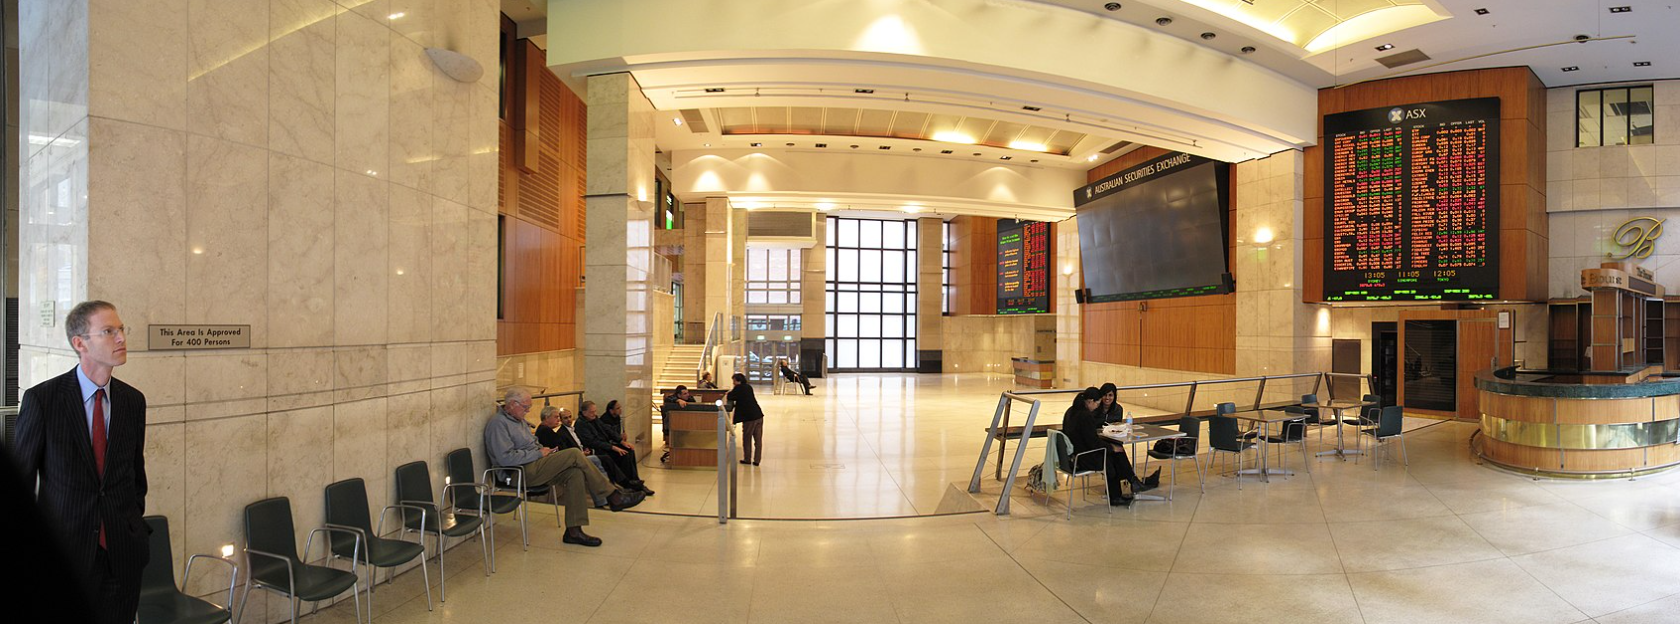
Australia Securities Exchange (ASX) Lobby
What is an IPO?
An IPO is a crucial stage at which a private company becomes publicly traded. This offering enables private companies to access a public stock exchange, such as the ASX, thereby tapping into larger financial markets to secure the equity capital necessary for expansion. By offering shares to the investing public, an IPO provides a way for early backers to raise capital. When a company goes public, it enhances its visibility. This can significantly increase the company’s valuation and open doors to new business opportunities, making an IPO float a viable strategy for growth.
The First IPO in History
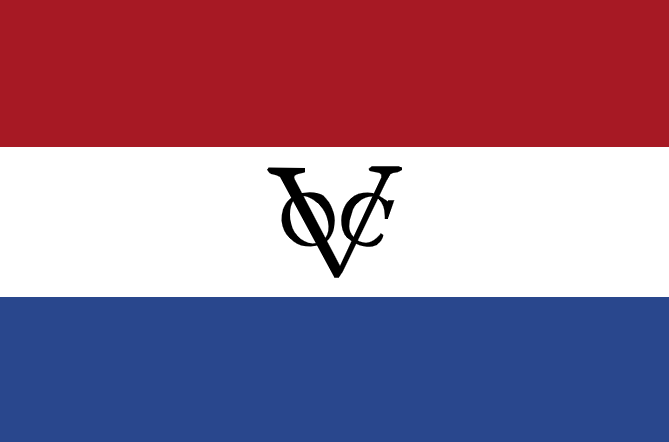
Dutch East India Flag – Source: Wikipedia
The history of the first public company can be traced back to the formation of the Dutch East India Company (Vereenigde Oost-Indische Compagnie or VOC) in 1602.
This pioneering entity was a private corporation established during the Dutch Golden Age, a period when the Netherlands was a beacon of commerce, art, and scientific discovery. The VOC was established to conduct colonial and trade activities in Asia. Given the high demand for spices in Europe for food preservation and flavouring, it was granted a monopoly over the Dutch spice trade, a lucrative market at the time.
The VOC’s services were essential due to the complexity and high costs associated with trading with Asia. Voyages were perilous, long, and expensive, with ships needing to navigate uncharted waters and confront various risks, including piracy and adverse weather conditions. The Dutch government recognised the strategic and economic importance of such voyages and authorised the VOC to act with considerable authority, allowing it to establish trading posts, engage in military actions, and govern acquired territories.
The VOC’s establishment as the first company to issue an IPO marked a watershed moment in financial history. Offering shares and bonds, the VOC turned to the investing public to raise capital to fund its expansive trading operations. This move democratized wealth beyond the aristocracy, enabling ordinary citizens to invest in and partake in the profits of international trade. The IPO process was facilitated through the Amsterdam Stock Exchange, the world’s first stock exchange, where these shares could be bought and sold.
The IPO mechanism brought substantial advantages to the VOC. It enabled the aggregation of enough capital to outfit a robust fleet of ships, and corporate finance, spread risks across a wider group of investors, and solidify the company’s financial base. This influx of public investment bolstered the VOC’s trading capacity and supported its expansive colonial endeavours. In return for equity capital, shareholders were entitled to a share of the profits from the spice trade and other ventures the company undertook.
The VOC’s successful initial public offering set a precedent, showcasing the immense potential of public capital markets. It illustrated how pooling resources from a broad base of investors could fund large-scale commercial projects that individual entities could not undertake alone.
This process improved the VOC’s capacity to operate internationally and laid the foundational structure for modern corporations and financial markets. It proved that an IPO could be a viable and effective exit strategy for businesses seeking to expand their horizons.
The IPO Process
The journey towards an IPO in Australia is a complex and highly regulated process that can be broken down into several distinct phases. Each step is designed to ensure transparency for potential investors and compliance with strict regulatory standards.
Step 1: Appoint Lead Managers and Advisors
Before initiating the IPO, the company assembles a team of experts. This process typically includes appointing a lead manager or investment bank to act as underwriters, as well as legal, accounting, and tax advisors. This team will guide the company through every stage of the IPO, from structuring the offer to managing regulatory filings.
Step 2: Due Diligence and Structuring
The company, with its advisors, undertakes a rigorous due diligence process. This involves a thorough review of all aspects of the business, including its financials, operations, legal structure, and contracts. The findings from this process are used to structure the IPO, determining the number of shares to be offered and the proposed use of the funds raised.
Step 3: Prepare the Prospectus
An IPO prospectus is the key disclosure document for an IPO. It is prepared in accordance with the Corporations Act and ASIC regulations. This document provides potential investors with detailed information about the company’s business model, financial performance, risks, and strategic outlook. Crafting the prospectus is a meticulous task that involves input from the entire advisory team to ensure accuracy and compliance.
Step 4: Lodge Prospectus and ASX Application
Once finalised, the prospectus is lodged with the Australian Securities and Investments Commission (ASIC). Following this, the company formally applies for admission to the official list of the ASX. The ASX will review the application against its listing rules (eligibility requirements) to determine if the company is suitable for public listing.
Step 5: Marketing and the Roadshow
With the prospectus lodged, the marketing phase begins. The company’s management team and the underwriters conduct a “roadshow,” presenting to institutional investors and brokers. The goal is to build interest and gauge demand for the IPO, which helps determine the final offer price.
Step 6: The Offer Period and Pricing
During the offer period, the prospectus is made available to the public, and investors can buy shares. At the end of this period, the company and its underwriters will close the offer and set the final IPO price, balancing the supply of shares available with investor demand. The offering is usually a new issue of stock.
Step 7: Allotment and Official Listing
After pricing, the IPO shares are allocated and allotted to successful applicants. The company then meets the final ASX listing requirements. On the agreed date, the company’s shares commence public trading on the ASX, marking the completion of the IPO process.
Implications and Future Prospects
Immediate Implications:
Following an IPO, a firm adjusts its corporate structure to meet the demands of being a publicly listed company. The company may now be able to raise additional capital, but it also becomes vulnerable to market forces. New funding makes expansion possible, but managing the increased vulnerability to market fluctuations and the commencement of public trading calls for a steady hand. The company must now regularly disclose financial information in accordance with the rules of public ownership.
Long-term Prospects:
A company’s financial performance and its ability to cultivate strong institutional investor connections are paramount in the dynamic IPO market. An IPO may frequently open the door for a secondary offering (or a follow-on offering), allowing the business to capitalise on increased stock market confidence. This visibility can attract beneficial alliances and mergers, thereby solidifying the company’s public image.
Key Questions About IPOs
What happens to existing shareholders in an IPO?
In an IPO, existing shareholders may experience dilution due to the issuance of new shares. However, the value of their holdings could increase. Early investors may benefit from the liquidity an IPO provides, as they can sell shares more easily on the public market after the issuance date. Company insiders may be subject to “lock-up” periods before they can sell their shares in the offering.
What is the risk of an IPO?
To make an informed decision and invest in an IPO, it is essential to understand the associated risks. These include market volatility, which can lead to unpredictable stock performance. There’s also the risk of not meeting market expectations. Additionally, the company (or issuer) offering shares of its stock faces increased regulatory scrutiny from bodies like the Securities and Exchange Commission. Participating in an IPO requires a thorough risk assessment.
Why would a company pursue an IPO?
An IPO is primarily intended to raise capital from the public by selling shares of a company. This influx of funds can be used for growth. An IPO also provides market validation. Additionally, being newly public offers liquidity for private shareholders and a mechanism for future fundraising. The use of IPO funds is a key part of the IPO strategy.
How is a company valued in the IPO process?
A company’s valuation for an IPO is a critical step. An investment bank considers the company’s financial health, industry comparisons, and market demand from institutional investors. Feedback from the roadshow helps refine the final valuation, culminating in the determination of the final IPO price for the shares being offered directly to the public.
How much does an IPO cost?
The cost of an IPO can be substantial. Expenses include underwriting fees, legal services, and registration fees. The listing requirements can also add to the cost. A company must assess these potential costs carefully against the anticipated benefits of listing on the ASX. The largest IPO can be an expensive process.
How Greenwich Capital Partners Can Help:
Greenwich Capital Partners provides financial advisory services to help businesses navigate the complexities of IPOs. Greenwich designs tailored strategies for each client, ensuring a well-structured approach to the IPO process, from due diligence to a successful listing on the ASX. Greenwich also supports managing the increased public attention that accompanies a market offering (or a new issue). Following its IPO, Greenwich continues to engage, assisting companies in adapting to the public market.